Quick answer
This Trupanion review looks at who gets real value from direct vet payment and unlimited payouts, and who might not. Is Trupanion worth it? Yes, if you want unlimited payouts and the convenience of direct vet pay at checkout. Your pet is young with a clean medical history. Trupanion is one of the few insurers that can pay the participating vet directly, skipping the usual pay-upfront-then-wait-for-reimbursement cycle (see our Healthy Paws review). The tradeoff: premiums run above average, there’s no wellness plan, and the policy doesn’t cover exam fees.
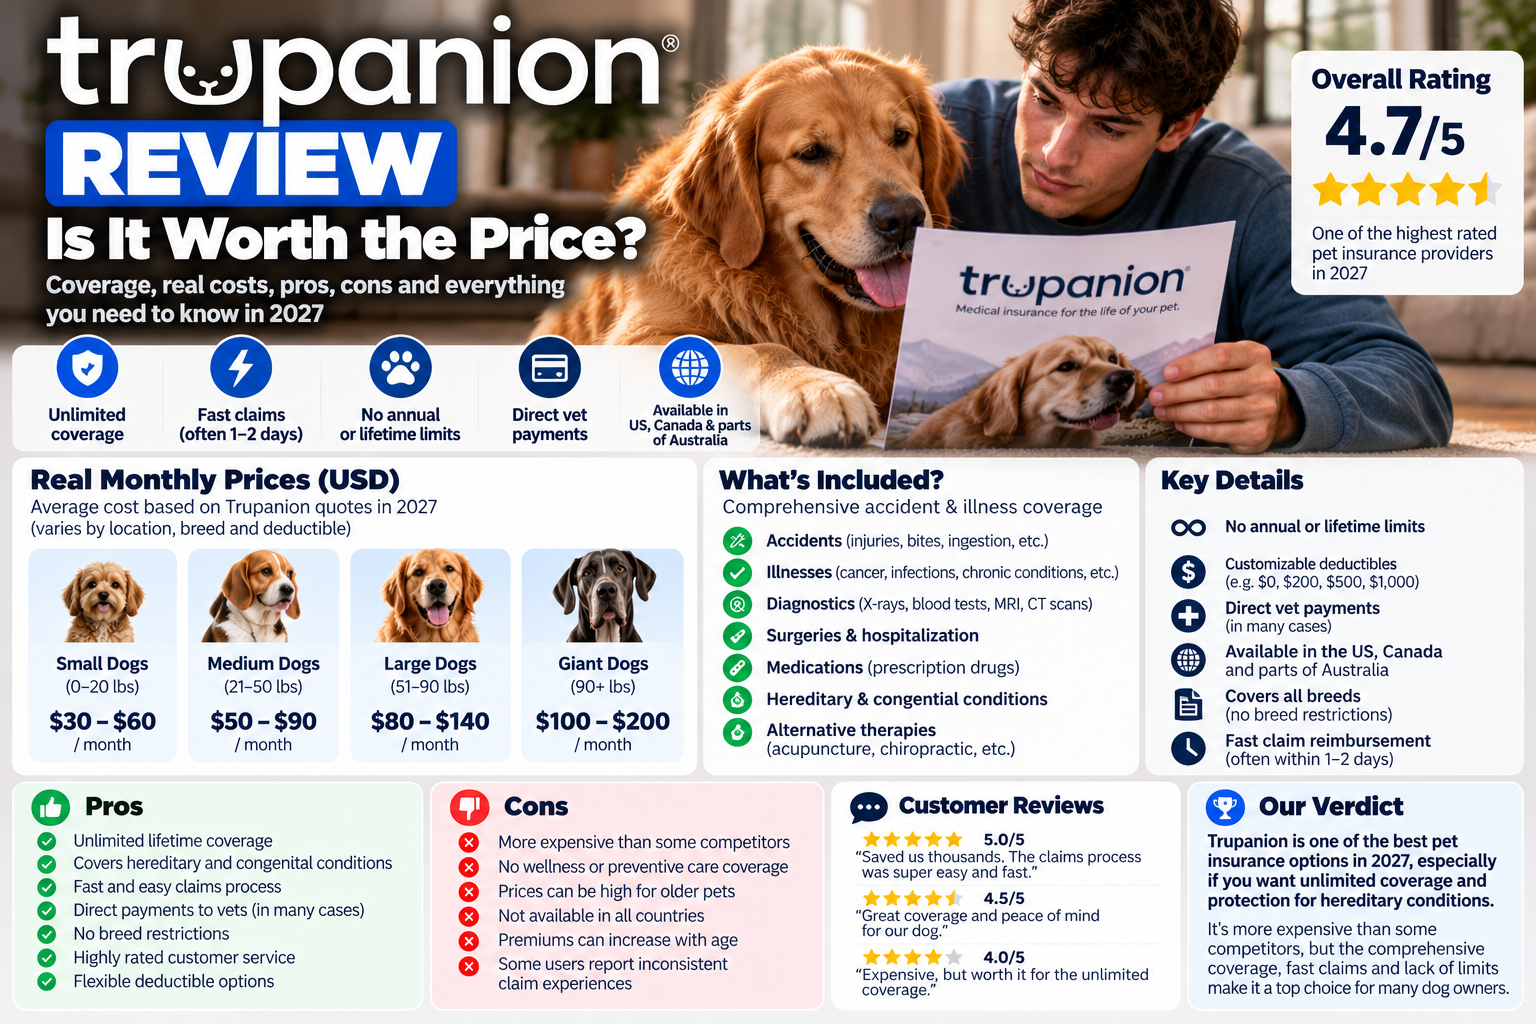
Trupanion has insured pets since 2000 and underwrites its own policies rather than reselling someone else’s. This is part of why direct vet pay works at thousands of clinics. Its coverage model is also unusual: instead of a single annual deductible, you pay a per-condition deductible once, then 90% of eligible costs for that condition are covered for life.
Pricing, deductibles, and the per-condition deductible
Trupanion’s pricing structure looks familiar at first — pick a deductible, get reimbursed a percentage (see how pet insurance deductibles work) (see pet insurance reimbursement rates). But the deductible itself works differently from most competitors.
| Variable | Detail |
|---|---|
| Reimbursement | 90% of eligible costs after the deductible |
| Deductible options | $0 to about $1,000, chosen per condition |
| Annual/lifetime limit | Unlimited |
| Sample price — dog (2-year-old mixed breed, Hartford, CT) | $136.96/mo at $100 deductible; $78.59/mo at $500; $47.39/mo at $1,000 |
| Sample price — cat (2-year-old shorthair, Hartford, CT) | $44.86/mo at $100 deductible; $27.85/mo at $500 or $1,000 |
| Optional riders | Recovery & complementary care (acupuncture, physical therapy) from ~$1.80–$8.52/mo; pet owner assistance (lost-pet reward, cremation) ~$4.95/mo |
For comparison, NAPIA-cited industry data puts the average dog accident-and-illness premium at around $53/month. Trupanion runs noticeably above that average unless you pick a high deductible.
The per-condition deductible, explained simply: instead of one deductible you pay once a year no matter how many things come up, Trupanion has you pay your chosen deductible amount once per new condition. Then that condition is covered at 90% for as long as your pet has it. So if your dog is diagnosed with a chronic illness like diabetes, you pay the deductible once. Every vet visit tied to that diabetes afterward is reimbursed at 90% — no new deductible each year. A separate accident later (say, a broken leg) triggers its own, new deductible.
How direct vet pay actually works
Most pet insurers make you pay the full bill up front and wait days for reimbursement. Trupanion is one of the few that can skip that step entirely, at clinics that participate in its program.
- You check in for the appointment and let the front desk know you have Trupanion
- At checkout, the clinic’s software (via Trupanion’s integration) submits the claim in real time
- Trupanion approves and pays its share directly to the clinic before you leave
- You only pay your portion — the deductible and the 10% you’re responsible for, plus anything not covered (like the exam fee)
This only works if the clinic uses compatible practice-management software and has signed up for the program. Not every vet offers it, especially smaller or rural practices. If your vet doesn’t support direct pay, you pay in full and file for reimbursement the normal way, just like with any other insurer.
Pros and cons
Pros
- Unlimited payouts: no annual or lifetime cap
- Direct vet pay at participating clinics — often no claim filing at all
- No breed exclusions: every breed is eligible
- Covers hereditary and congenital conditions (like hip dysplasia) if no symptoms showed before enrollment
- Per-condition deductible means no repeat deductible for an ongoing chronic illness
Cons
- Premiums run above the market average, especially at low deductibles
- No wellness plan for routine care
- Exam fees are never covered, even for a covered condition
- Pre-existing condition rules are strict: anything with symptoms before enrollment is excluded for life
- Direct pay only works at clinics that support the integration — not universal
Exclusions, waiting periods, and ratings
Main exclusions (see what pet insurance doesn’t cover)
- Exam fees and sales tax on the bill
- Routine and preventive care: vaccines, preventive medications, spay/neuter
- Pre-existing conditions, including recurring injuries from before enrollment
- Preventable conditions, such as dental disease when recommended cleanings were skipped
- Elective or cosmetic procedures (tail docking, declawing)
Waiting periods (see pet insurance waiting periods)
Sources differ slightly on the exact numbers, so always confirm at quote time. But a typical range is 5 days for injuries and 30 days for illnesses, with longer waits for specific conditions like hip dysplasia.
Ratings at a glance
| Source | Score |
|---|---|
| Insurify | 4.7/5 (~18,000 reviews) |
| Trustpilot | 4.2/5 (6,700+ reviews) |
| BBB / Yelp | Mixed — lower scores, with complaints about denied claims and rising premiums |
Trustpilot reviewers tend to praise the coverage itself, the support team, and the direct-pay experience. Lower-rated reviews elsewhere cluster around pre-existing condition denials and premiums that climb as pets age.
Who it’s best for, and FAQ
Best for
- Pet owners whose vet supports direct pay and want to avoid paying upfront for big bills
- Owners of breeds prone to hereditary or congenital conditions, since Trupanion covers every breed with no exclusions on that front
- Anyone who wants true unlimited coverage for a serious chronic illness
- Pet parents who enroll young, before any symptoms of a future condition appear
Not the best fit for
- Budget-conscious owners, since premiums run above average, especially at low deductibles
- Anyone who wants routine/wellness care bundled in
- Owners whose vet doesn’t support direct pay — you lose Trupanion’s signature feature and file claims like with any other insurer
FAQ
Does Trupanion cover pre-existing conditions? No. Any condition that showed symptoms before your policy started is excluded for life, including recurring injuries.
What is a per-condition deductible? Instead of one deductible per year, you pay your deductible once for each new condition, then that condition is covered at 90% going forward. No repeat deductible for the same chronic illness.
Does every vet offer direct pay? No. Only clinics with compatible practice-management software and enrollment in Trupanion’s program can pay claims at checkout; otherwise you pay upfront and get reimbursed.
Are exam fees covered? No, exam fees are excluded on every Trupanion plan, even for a covered condition.
Bottom line
Trupanion’s direct vet pay and unlimited payouts solve two of the biggest frustrations with pet insurance. Fronting a huge bill and watching your coverage run dry on a long chronic illness. You pay for that convenience with a higher-than-average premium and zero help with routine care.
If your regular vet already supports direct pay, Trupanion is hard to beat for peace of mind on a serious diagnosis. If not, you’re paying premium prices for a feature you can’t actually use — worth comparing against and other unlimited-payout insurers before deciding.
Sources
- Trupanion pet insurance review — Insurify
- Trupanion Pet Insurance Review — NerdWallet
- Trustpilot — Trupanion reviews
- Better Business Bureau — Trupanion profile
Sources
- Trupanion pet insurance review — Insurify — insurify.com
- Trupanion Pet Insurance Review — NerdWallet — nerdwallet.com
Key Takeaways on Trupanion Review
- The main point of this Trupanion review: it offers unlimited payouts and direct vet pay at checkout.
- It works best for a young pet with a clean medical history.
- Premiums rise as pets age, so review the price every year.
By Joaquín Benicio Conforti · Last updated: October 2026